Quick Answer
A Mauritius Global Business Company (GBL) is governed by the Financial Services Act 2007 and overseen by the FSC, designed for foreign-owned businesses operating principally outside Mauritius while still qualifying as Mauritius tax residents. It requires genuine substance, at least 2 resident directors, a local principal bank account, and accounts audited in Mauritius in exchange for tax treaty access and an 80% Partial Exemption Regime on qualifying income. Incorporation typically takes 5 to 8 working days.
If you're researching a Mauritius Global Business Company, you've probably already noticed this structure comes up constantly for founders looking to combine genuine tax treaty access with a credible, well-regulated jurisdiction, and that reputation is backed by real legislation, not just marketing.
At Neptune Fiduciaries Group, I've worked with founders who assumed a Global Business Company would work like a lighter offshore entity, only to discover it comes with genuine substance requirements: resident directors, local bank accounts, and audited accounts that set it apart from more minimal offshore structures entirely.
This guide breaks down exactly what a Mauritius Global Business Company is, what it requires to stay compliant, the tax benefits it actually offers, and the real process and costs involved in setting one up properly.
Start Your Global Business
Journey Today
Whether you're launching a new venture or expanding globally, our experienced advisors provide tailored corporate and banking solutions designed for long-term success.
What Is a Mauritius Global Business Company?
A Mauritius Global Business Company, commonly referred to as a GBL, is governed by the Financial Services Act 2007 (FSA) and the Companies Act 2001, and falls under the oversight of the Financial Services Commission (FSC). It's a Mauritian entity specifically designed to conduct lawful business activity principally outside of Mauritius.
A resident corporation is required to apply for a GBL where the majority of its shares, voting rights, or legal and beneficial interest is held or controlled by non-citizens of Mauritius, and where that corporation conducts or proposes to conduct business principally outside Mauritius, or with a category of persons specified under the FSC Rules.
This dual condition foreign ownership combined with genuinely international business activity is exactly what distinguishes a GBL from a purely domestic Mauritian company. It's built specifically for internationally owned and operated businesses that still want to benefit from Mauritius's tax residency status.
Understanding this foundational structure sets up exactly why the GBL carries the specific characteristics and substance requirements it does, which is precisely what makes it such a genuinely useful, if more demanding, structure compared to lighter offshore alternatives.
For a broader look at international business structures, an International Business Company may also be worth exploring. Explore International Business Company formation for more details.
Main Characteristics of a Mauritius Global Business Company
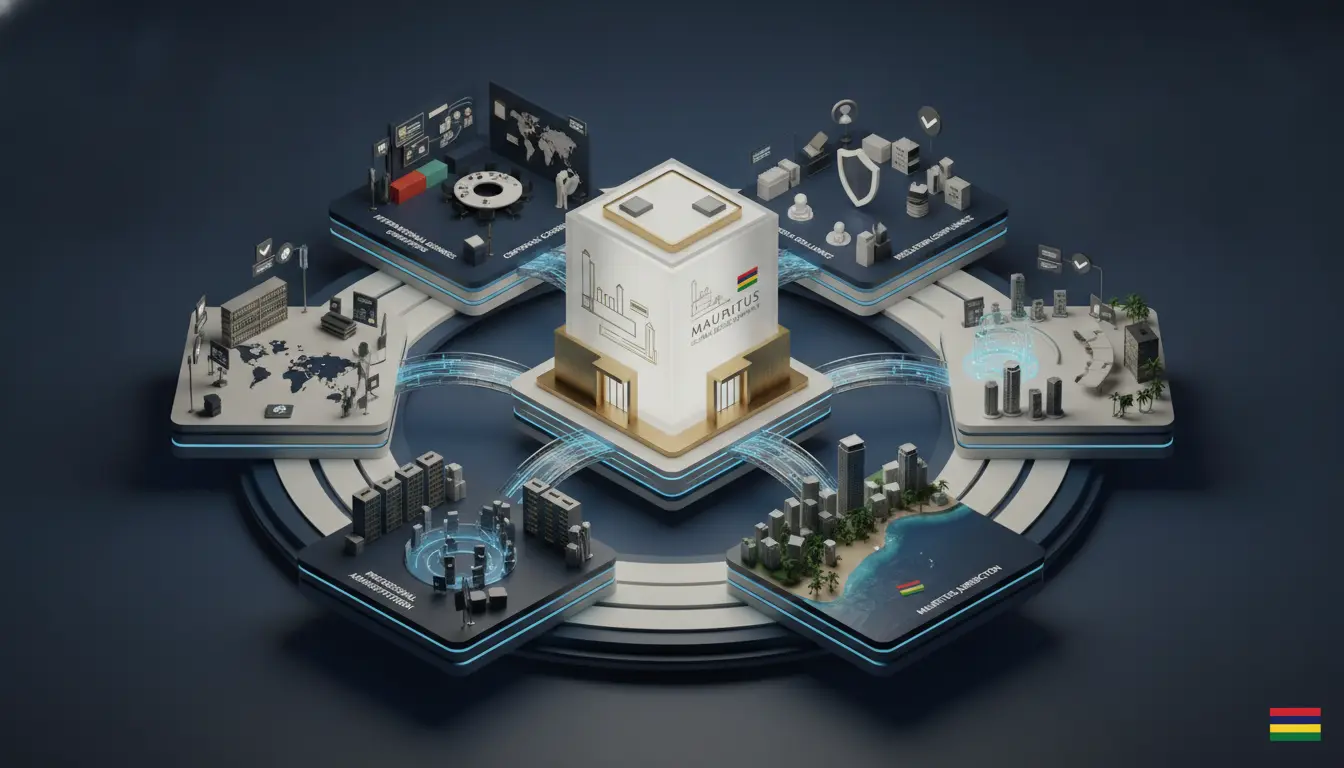
Before diving into the compliance side, it helps to understand what actually makes a GBL distinct from other Mauritius entity types available to international founders.
- Central management and control in Mauritius: This is required specifically for tax residency purposes and eligibility for a Tax Residence Certificate, which is the foundation of everything else the structure offers.
- Qualification as a Mauritian tax resident: Because of this residency status, a GBL can access Mauritius's genuinely extensive tax treaty network, which is one of the structure's biggest practical advantages for cross-border business.
- Access to the Partial Exemption Regime: A GBL can benefit from partial exemption on specific categories of income, covered in more detail later in this guide.
- Flexible company status options: A GBL can be structured as a public or private company, and can also take on Limited Life Company status, Protected Cell Company status, or Variable Capital Company status, among other structuring options.
These characteristics work together to explain why a Mauritius Global Business Company appeals specifically to founders who want genuine tax residency and treaty access, not just an offshore label; however, achieving that status comes with real, defined obligations around management and control.
Requirements to Be Managed and Controlled from Mauritius
This is where the GBL genuinely distinguishes itself from lighter offshore structures, since the FSC requires real substance rather than a nominal Mauritius presence. A GBL must, at all times, carry out its core income-generating activities in or from Mauritius as required under the Income Tax Act, be administered by a licensed Management Company, and be managed and controlled from Mauritius itself.
To actually satisfy this "managed and controlled from Mauritius" test, the company needs to meet all of the following conditions:
- At least two resident directors in Mauritius: This is the baseline requirement for demonstrating genuine local management rather than a nominal presence, and both directors need to be actively involved in real decision-making rather than serving in name only.
- Principal bank account maintained in Mauritius: The company's main banking relationship needs to stay based in Mauritius at all times, not merely opened there once and then operated primarily through an overseas account for convenience.
- Accounting records kept at the registered office in Mauritius: Financial records need to be physically maintained locally, not held remotely elsewhere, ensuring regulators and auditors can access complete documentation directly from within the jurisdiction.
- Statutory financial statements prepared and audited in Mauritius: The audit itself must happen within Mauritius rather than being outsourced to an overseas auditor, reinforcing that the company's financial oversight genuinely sits within the country.
- Director meetings including at least two Mauritius-resident directors: Board meetings need genuine local director participation, reinforcing that real decisions are being made from within Mauritius.
Meeting all five of these conditions isn't optional if you want the GBL to actually qualify for its tax residency status and treaty benefits; skipping even one can jeopardize the very advantages that make this structure worthwhile in the first place.
If you're weighing this against broader offshore compliance obligations, this is worth a read too: Legal Requirements for Offshore Companies You Must Know.
Key Features of a Mauritius Global Business Company
Beyond the management and control test, a Mauritius Global Business Company carries a specific set of ongoing compliance features that founders need to plan for well before incorporation.
- Company secretary and registered address required: Every GBL must maintain a company secretary and a registered address within Mauritius as a standing requirement.
- Annual audited accounts filed with the FSC: These need to be submitted within 6 months following the company's financial year-end, keeping the licence in good standing.
- Privacy for private GBL registers: Registers filed with the Registrar of Companies (ROC) for a private GBL aren't available to the public, offering a genuine degree of confidentiality.
- Annual tax return filed with the MRA: Also due within 6 months following the financial year-end, this runs alongside the FSC filing as a separate compliance obligation.
- Advance Payment System (APS) applicability: APS applies to all companies except where, in the preceding financial year, gross income didn't exceed MUR 10 million, or the company had no chargeable income.
- Additional certification if part of the activity happens in Mauritius: In that case, the company must submit, alongside its audited financial statements, a director-signed report certifying compliance with the FSA and relevant FSC rules, plus an auditor's certificate confirming the percentage of business conducted in Mauritius.
These features make clear that a GBL isn't a set-and-forget structure; it demands genuine, ongoing compliance attention every financial year, which is exactly why understanding the full picture upfront matters more than it might for lighter offshore entities.
For a broader understanding of international structures, Offshore Company Formation is another option worth exploring. Explore offshore company formation to learn more.
The Partial Exemption Regime: What Income Qualifies
The Partial Exemption Regime is one of the most valuable and specific benefits available to a properly structured International Company Formation, exempting 80% of certain qualifying income categories from tax. These categories include income attributable to a permanent establishment in a foreign country, foreign dividends, interest income, and income derived by a Collective Investment Scheme, Closed End Fund, CIS manager, CIS administrator, investment advisor, or asset manager licensed and approved by the FSC.
The regime also covers income from ship and aircraft leasing, leasing and provision of international fibre capacity, reinsurance and reinsurance brokering, and income from the sale, financing arrangement, and asset management of aircraft and spare parts, including related aviation advisory services.
There's an important trade-off worth understanding before claiming this exemption: a GBL company cannot claim credit for foreign tax actually paid on income where it has already claimed the partial exemption, so founders need to weigh which approach genuinely benefits their specific tax position. The exemption can also only be claimed where prescribed substance requirements are properly met, tying back directly to the management and control conditions covered earlier and, as a further benefit, a GBL is exempted from Corporate Social Responsibility (CSR) obligations altogether.
Cost of Setting Up a Mauritius Global Business Company: Full Breakdown
Understanding the real cost of setting up a Mauritius Global Business Company means accounting for both incorporation fees and the ongoing costs tied to its substance and compliance requirements.
| Cost Item |
Typical Range (MUR) |
| FSC application/licence fee |
Set by the FSC's published fee schedule, payable at application |
| Company incorporation service |
MUR 40,000 to 90,000, depending on formation provider |
| Management Company administration (annual) |
MUR 80,000 to 200,000+ per year, mandatory ongoing requirement |
| Resident directors (2 minimum, annual) |
MUR 60,000 to 150,000+ per year, depending on provider |
| Annual audit and financial statement preparation |
MUR 40,000 to 100,000+ per year |
| Registered office and company secretary (annual) |
MUR 30,000 to 70,000 per year |
Given the mandatory Management Company administration, resident directors, and local audit requirements, ongoing annual costs for a GBL tend to run higher than lighter offshore structures, but this is exactly the cost of the genuine substance that makes the tax treaty benefits and residency status legitimately available.
If you're considering other offshore jurisdictions, Seychelles Offshore Company Formation is another structure worth exploring. Explore Seychelles Offshore Company Formation for more details.
Why Choose Neptune Fiduciaries Group for Mauritius GBL Formation
Understanding the FSC's substance requirements on paper is one thing; actually arranging qualified resident directors, a compliant Management Company relationship, and the banking and audit infrastructure a GBL needs is where founders benefit most from experienced guidance. This is exactly where Neptune Fiduciaries Group comes in, helping structure a Mauritius Global Business Company that satisfies every management and control condition from day one.
Handling offshore and treaty-jurisdiction company formation, International Business Company formation daily means seeing the same avoidable issues come up repeatedly. GBLs that technically incorporate but fail to genuinely meet the five-point management and control test, or founders claiming the Partial Exemption Regime without confirming the underlying substance requirements are actually satisfied.
Whether the goal is accessing Mauritius's tax treaty network, structuring an internationally owned holding company, or building a properly compliant GBL from the ground up, having a partner who understands both the FSC's requirements and the practical realities of ongoing substance compliance makes the entire process considerably more reliable.
Start Your Global Business
Journey Today
Whether you're launching a new venture or expanding globally, our experienced advisors provide tailored corporate and banking solutions designed for long-term success.
Conclusion
A Mauritius Global Business Company offers a genuinely strong combination of tax treaty access, Partial Exemption Regime benefits, and real regulatory credibility, but unlike lighter offshore structures, it demands genuine substance: resident directors, local banking, and audited accounts all based in Mauritius itself.
Getting it right comes down to confirming your business genuinely satisfies the management and control test, understanding exactly which income categories qualify for partial exemption, and budgeting properly for the ongoing Management Company and compliance costs involved. Done correctly, a GBL remains one of the more credible and tax-efficient structures available for founders serious about long-term, treaty-backed international business.
Whether the priority is genuine tax treaty access, credibility with international banks, or building a structure that satisfies real substance requirements rather than a nominal offshore presence, a properly established GBL delivers exactly that provided every management and control condition is met from the very first year.
FAQs
Does a Mauritius Global Business Company need resident directors?
Yes, at least two resident directors in Mauritius are required as part of satisfying the "managed and controlled from Mauritius" test necessary for tax residency status.
Is a Mauritius Global Business Company subject to tax?
Yes, but as a Mauritius tax resident, a GBL can access the country's tax treaty network and benefit from the Partial Exemption Regime, which exempts 80% of specific qualifying income categories from tax.
How long does it take to set up a Mauritius Global Business Company?
A GBL can typically be incorporated within 5 to 8 working days from the time all required information is provided to the relevant authorities.
What's the difference between a GBL and an Authorised Company in Mauritius?
A GBL is treated as a Mauritius tax resident with access to the tax treaty network but requires genuine local substance, including resident directors, while an Authorised Company is treated as non-resident for tax purposes with lighter statutory requirements but no treaty access.